Business
The Behavioural Warning Signs That Someone May Be Struggling in Silence

People do not always say when something is wrong. Many continue going to work, replying to messages, attending family events, and laughing at jokes while carrying a private burden that nobody else can see.
Silence can come from shame, fear, confusion, or a desire not to worry other people. Some people believe they should deal with their problems alone. Others do not yet understand what they are feeling. Rather than asking for support, they begin to change in small but noticeable ways.
One difficult day does not always point to a serious issue. Everyone gets tired, cancels plans, loses patience, or lets household chores pile up from time to time. Concern becomes more reasonable when several changes happen together, continue for weeks, or begin to affect work, relationships, money, health, and everyday responsibilities.
Recognising these patterns does not mean diagnosing someone. It means paying attention. A friend, relative, colleague, or partner may need a safe conversation long before they feel ready to ask for one.
When Someone Starts Pulling Away
Isolation is one of the most common signs that a person is struggling. Someone who once enjoyed company may begin turning down invitations, ignoring calls, leaving events early, or spending most of their free time alone.
At first, the reasons may sound ordinary. They are busy. They feel tired. They forgot about the plan. They have work to finish. Each explanation may be believable, but a repeated pattern can suggest that something deeper is happening.
A person may withdraw because social contact has started to feel exhausting. They may worry that friends will ask questions they are not ready to answer. They may also fear that other people will notice changes in their mood, appearance, drinking, spending, or behaviour.
Isolation Is Not Always Obvious
Withdrawal does not always mean staying inside with the curtains closed. Some people remain active online while avoiding honest conversations. They may post photos, share jokes, or react to messages, yet never speak openly about how they feel.
They may still attend work meetings or family gatherings, but their emotional presence has changed. Conversations become brief. They seem distracted. They leave as soon as possible. They stop sharing personal news and begin answering every question with “I’m fine.”
It can be tempting to assume that the person no longer cares. In reality, they may be using most of their energy just to appear normal.
Isolation can have many causes. Grief, burnout, anxiety, depression, family conflict, physical illness, debt, and substance use can all lead someone to pull away. When withdrawal happens alongside heavy drinking, drug use, or a decline in daily functioning, support from an inpatient addiction treatment center can provide a structured place where the person receives care away from familiar triggers.
Still, loved ones should avoid making assumptions. The aim is not to decide what the problem is before the person speaks. The aim is to notice that something has changed and make it easier for them to talk.
Irritability Can Hide More Than Anger
A person in distress does not always look sad. Sometimes they look angry.
They may snap over small problems, become impatient during ordinary conversations, or react strongly to harmless questions. A forgotten item, a delayed reply, or background noise may trigger a response that seems far larger than the situation deserves.
This behaviour can be confusing and painful for the people around them. You may think, “Why are they treating me like this when I’m trying to help?” That reaction is understandable.
Here’s the thing. Irritability can act like emotional armour. When someone feels overwhelmed, frightened, ashamed, or out of control, anger creates distance. It discourages other people from asking difficult questions. It also allows the person to focus on an argument rather than the pain beneath it.
Watch for a Change From Their Usual Nature
The key is to compare the behaviour with the person’s usual character. Some people have always been impatient, blunt, or quick-tempered. The warning sign is a clear and lasting change.
A normally calm person may become defensive. Someone who usually handles stress well may start arguing with colleagues, family members, or strangers. They may interpret concern as criticism and simple questions as accusations.
It also helps to notice what happens after the anger passes. Do they seem embarrassed? Do they apologise and then withdraw? Do they struggle to explain why they reacted so strongly? These moments can show that the anger is not the whole story.
Poor sleep, work pressure, family strain, and financial worries can shorten anyone’s temper. Ongoing irritability paired with mood swings, secrecy, risky choices, or substance use deserves more attention. Professional behavioral health services in Massachusetts and similar services in other areas can assess emotional, mental health, and substance-related concerns. This matters because similar behaviours can have very different causes.
Caring about someone does not mean accepting harmful conduct. You can remain supportive while setting limits. A calm statement such as, “I want to listen, but I cannot continue this conversation while you are shouting,” shows care without allowing the situation to become unsafe.
Neglected Hygiene and Disrupted Routines
Changes in personal care can show that someone is finding daily life harder than it appears.
You may notice that they wear the same clothes for several days, stop washing their hair, neglect dental care, or seem less concerned about their appearance. Their bedroom, kitchen, car, or workspace may become unusually cluttered. Meals may consist of snacks, takeaway food, or nothing at all.
It is easy to label these changes as laziness. That judgement rarely reflects what is actually happening.
Small Tasks Can Feel Surprisingly Heavy
When a person feels mentally or physically drained, basic tasks can become difficult. Taking a shower is not just one action. It involves getting up, finding clean clothes, washing, drying, and preparing for whatever comes next. To someone with energy, that sounds simple. To someone struggling with depression, trauma, stress, or substance use, it can feel like a long climb.
Daily routines may begin falling apart in other ways. The person may stay awake all night and sleep through the day. They may skip meals, miss appointments, forget medication, or leave important letters unopened. Dishes pile up. Laundry stays in baskets. Food expires in the fridge.
These details can look minor from the outside, but they often show how much effort the person is using simply to get through the day.
Comments about their appearance can increase shame. Saying, “You look terrible,” or, “Why can’t you clean this place?” is likely to make them retreat further. A practical offer works better.
You could say, “You seem exhausted. I’m making dinner tonight, so I can bring you a plate.” You could also offer to help with washing, shopping, transport, or another specific task. Clear offers are easier to accept than the vague phrase, “Let me know if you need anything.” A person who feels overwhelmed may not know what to ask for.
Frequent Absences and Loss of Interest
A person’s schedule can reveal changes before they are ready to talk about them.
They may start arriving late to work, calling in sick, cancelling medical appointments, or disappearing for long periods. They might stop attending classes, training sessions, family meals, religious gatherings, or clubs they once enjoyed.
One missed event means little. Life happens. Repeated absences, poor explanations, and a decline in performance can form a more concerning pattern.
Sometimes the person genuinely feels unwell but cannot explain why. They may have headaches, stomach problems, exhaustion, or sleep difficulties caused by stress. In other cases, they may be dealing with the effects of drinking or drug use, including withdrawal, hangovers, disrupted sleep, and attempts to hide what is happening.
When Enjoyment Fades
Loss of interest can be just as revealing as absence. A person who loved football may stop watching matches. Someone who enjoyed cooking may live on toast and coffee. A keen gardener may stop caring for plants. Music, hobbies, friendships, and weekend plans may no longer hold their attention.
They may describe this as boredom, but it often feels more like emotional numbness. Activities that once brought pleasure now feel tiring or pointless.
This change can appear during depression, grief, burnout, trauma, chronic stress, and substance-related problems. It can also happen when a person spends most of their time hiding a problem, recovering from substance use, or planning how to obtain more alcohol or drugs.
Some people need a safe break from the routines and pressures that keep the cycle going. A programme providing luxury detox and residential treatment can offer privacy, medical support, and a stable setting. The right type of care should always depend on a professional assessment and the person’s actual needs, not the appearance or name of the programme.
When talking to someone who has lost interest in people or activities, focus on what you have noticed. Avoid guilt-based comments such as, “You never make an effort anymore.” A gentler approach would be, “You haven’t joined us for Sunday lunch lately, and I’ve missed seeing you. How have you been feeling?”
That wording leaves room for an honest answer.
Secretive Behaviour and Unpredictable Money Problems
Everyone has a right to privacy. Secrecy is different because it often appears as a sudden change.
A person may begin hiding their phone, leaving the room to take calls, or giving unclear answers about where they have been. Their explanations may change. They may become defensive when asked simple questions or accuse others of being controlling.
One private conversation or locked phone does not prove anything. Concern grows when secrecy appears alongside other changes such as absences, mood swings, isolation, or financial trouble.
Money Trouble Can Be an Important Clue
Financial problems often create visible cracks in a person’s routine. Bills remain unpaid. Rent money disappears. They borrow small amounts from several people. They may sell belongings or ask for urgent loans without giving a clear explanation.
Their spending may also become hard to predict. They have no money for food one day, then spend freely a few days later. Bank alerts make them anxious. Letters remain hidden. They may avoid talking about work hours, wages, or debts.
These patterns can have many causes. Job loss, gambling, coercive control, medical costs, debt, fraud, and substance use can all lead to sudden money problems. Loved ones should not decide on the cause without evidence.
Ask what is happening, but avoid turning the conversation into an interrogation. It is also sensible to avoid giving cash when the situation feels unclear. Practical help can be safer. You might pay for groceries directly, provide transport, or help the person speak with a debt adviser.
When alcohol or drugs are involved, a drug and alcohol rehab in New Jersey or another suitable treatment provider can help address both substance use and the habits surrounding it. Families may need support too, especially when trust and money have become sources of conflict.
How to Begin a Supportive Conversation
Starting a conversation about someone’s wellbeing can feel awkward. Many people delay because they fear using the wrong words, causing offence, or making the situation worse.
But silence sends a message too. It can make the person believe that nobody has noticed or that nobody wants to hear the truth.
You do not need a perfect speech. Choose a calm moment and a private place. Avoid starting the conversation during an argument, when the person is intoxicated, or when either of you is rushing somewhere.
Speak About What You Have Seen
Focus on clear observations rather than labels.
You could say, “I’ve noticed you’ve missed work several times and haven’t been replying to friends. I’m concerned about you.”
That approach is more helpful than saying, “You’re depressed,” or, “You must be taking drugs.” Labels can make the person feel judged before they have had a chance to speak.
Ask simple, open questions. “How have things been lately?” is often enough to begin. You can also ask what has felt hardest, whether they feel safe, or what kind of support would help today.
Then pause.
Silence can feel uncomfortable, but do not rush to fill it. The person may need time to decide whether it is safe to be honest. Listen without checking your phone, correcting details, or preparing your next reply.
Do Not Turn the Talk Into an Interrogation
Concern can make people ask too many questions at once. Slow the conversation down.
You do not need every detail during the first talk. The goal is to help the person feel less alone, not to complete an investigation. You can say, “You don’t have to explain everything today. I just want you to know I’m here.”
They may deny that anything is wrong. They may change the subject or become defensive. Stay calm. Let them know that the door remains open.
Urgent danger requires a different response. If someone talks about suicide, threatens harm, loses consciousness, shows severe withdrawal symptoms, or appears medically unsafe, contact emergency services. Do not leave the person alone while waiting for help when it is safe for you to remain with them.
Support Without Taking Over
Caring for someone does not mean becoming their therapist, financial adviser, driver, crisis worker, and secret keeper all at once.
Trying to manage every part of another person’s life can exhaust you. It may also prevent them from taking responsibility for their own choices.
Offer steady and practical support. Help them arrange an appointment. Sit beside them while they call a service. Drive them to a consultation. Check in the following day. These small actions can make the first step feel less frightening.
But keep reasonable boundaries. You cannot force someone to be honest. You cannot control their recovery through effort alone. You can encourage them, listen carefully, and respond when danger appears. You can also seek advice for yourself.
The behavioural warning signs of silent distress are rarely neat. Isolation, anger, neglected hygiene, absences, loss of interest, secrecy, and money problems often overlap. Some changes have simple explanations. Others reveal pain that has been hidden for months.
What matters is the pattern and the change from the person’s usual behaviour.
Notice without spying. Ask without accusing. Listen without rushing to fix everything.
Sometimes the first step towards support is not a dramatic intervention. It is one person saying, calmly and sincerely, “You don’t seem like yourself lately, and I care about what’s happening.”


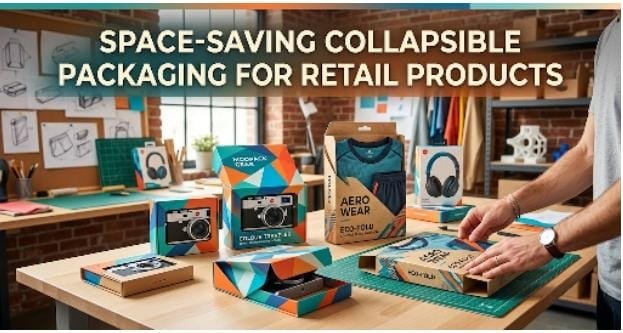
The storage of products is expensive. Not only is warehouse space costly, but there is also a cost to storing goods. Products that are kept in a box just waiting to be filled are a problem. After they are done waiting, the final bill will remind you of it.
Here’s how collapsible rigid packaging makes its case. It folds away to a small package when not in use, and snaps back when it needs to be. Not complicated, and an excellent problem-solver.
What Collapsible Packaging Actually Solves
Standard rigid boxes have a footprint based on their contents or lack thereof. A hundred flat-packed boxes makes for a nicely stacked pile on a warehouse pallet. The same hundred pre-formed boxes makes for an expensive and large shipment of mostly air.
Collapsible packaging avoids that entirely. Flat when stored, shipped, or moved between facilities. Formed only when a product actually needs to go inside it.
Retailers running multiple locations feel this the most. Stockrooms are small. Shelf space is smaller still. Packaging that folds down to a fraction of its assembled size means more room for stock, not boxes.
Retail Products That Benefit Most
Not every product needs this. Heavy, bulky items usually ship fine in standard cartons.
Where collapsible packaging really shines is smaller retail goods. Cosmetics, accessories, homeware, gift items. Anything sold in reasonably high volume, where storage space adds up fast across hundreds or thousands of units.
Seasonal retail stock benefits too. A shop ordering extra packaging ahead of a busy period does not want a stockroom full of assembled boxes sitting there for weeks. Flat-packed packaging for products waiting for a seasonal rush takes up a fraction of the space.
Design Considerations That Actually Matter
Collapsible does not mean flimsy. A well-designed fold structure still protects the product properly once assembled.
Reinforced fold lines matter here and locking tabs help too. A box that folds into shape and locks without tape saves time on the shop floor. Staff assembling stock during a busy period do not want to be hunting for a tape gun every few minutes.
Branding Does Not Have to Suffer
There is a myth that collapsible designs limit branding options. Not really true anymore.
Print quality on flat-packed packaging for products matches standard cartons. The branding gets applied before the fold lines are cut, so logos, colours, and finishes look exactly as intended once the box is assembled. Customers browsing a shelf would not necessarily know the box folded flat before it reached the store.
Shipping and Storage Savings, Properly Broken Down
Flat-packed boxes are able to be packed more tightly on a pallet which reduces the number of lorries required for transportation reducing costs directly
Storage costs drop too. A stockroom holding flat packaging instead of assembled boxes can fit considerably more stock in the same footprint. For retailers paying for warehouse space by the square metre, this is not a small saving. It adds up across a full year of orders.
Handling time changes as well. Staff assembling packaging on demand only fold up the boxes that you need for that day’s stock, rather than storing pre set boxes that may sit idle without use for days.
Where It Falls Short
Worth being honest about this. Assembly takes staff time. Someone has to fold and lock each box before it comes in use, which is an extra step that pre-formed cartons do not require.
For very high-volume operations shipping thousands of units daily, that assembly time needs factoring into labour costs. It is not always the right fit for every business, particularly ones without spare hands during peak periods.
Getting It Right
Custom rigid boxes is most useful when dealing with small items, irregular sales throughout the year, and/or limited storage space. It’s also important to consider the additional labour that you need to assemble the package, though it’s probably worth testing on a small scale.
Ask the manufacturer to provide samples before investing in a large set. It’s a good idea to check the strength of a folded box, print quality, and how easy it is to open during a test run.
Good packaging for products does not have to sit around taking up space it is not using. Flat when it is not in need. Solid when it is. That is really the whole appeal.

Estate administration sounds simple on paper. Someone passes away, their wishes get carried out, everyone moves on with their lives. Reality rarely cooperates that neatly. Paperwork piles up. Emotions run high, sometimes higher than anyone expected. And small mistakes have a way of snowballing into legal headaches nobody saw coming. Handling an estate well takes patience. It also takes a fair amount of stubbornness, if we’re being honest.
Start by understanding what you’re actually on the hook for. Executors often assume the job is just handing out belongings and closing a few accounts. It isn’t. Debts need settling. Taxes need filing. Beneficiaries need notifying, all on a timeline that couldn’t care less about your schedule or your energy level that week. Many executors find real value in discussing your case with a probate attorney early, before the mistakes happen instead of after. That’s not weakness. It’s just common sense, sort of like reading the manual before assembling furniture, instead of winging it and ending up with three mystery screws and a wobbly shelf.
Don’t Skip the Inventory
Rushing through the asset inventory ranks among the biggest mistakes people make. Skipping it almost entirely ranks right up there too. Every account, every property, every possession needs clear documentation before anything gets distributed to anyone. Skip this step, even by accident, and you’ve opened the door to disputes down the road. Family members remember things differently. Especially when money enters the picture. A thorough inventory protects everyone involved, including you as the executor, from accusations that something went missing or got mishandled somewhere along the way.
So take photos of everything. Write it all down, even the details that seem painfully obvious in the moment. Arguments six months from now have a strange habit of hinging on exactly the kind of detail nobody bothered to record.
Watch Out for Deadlines
Estate administration comes loaded with deadlines, more than most people expect going in. Tax filings. Creditor notifications. Court paperwork with its own quiet clock ticking in the background. Miss one, and real problems follow, sometimes financial, sometimes legal, sometimes both at once. Set reminders wherever you can. Don’t lean on memory alone, because grief has an odd way of making even the simplest dates slip through the cracks.
Feeling overwhelmed by all of it? Break the deadlines into smaller pieces instead of staring at the whole pile. Tackle the tax paperwork one week, then the creditor notices the next. Slow and steady wins here, almost every single time.
Communicate With Beneficiaries
Silence breeds suspicion, plain and simple. Go months without an update, and beneficiaries start assuming the worst. Honestly, who could blame them? Regular communication, even something brief, keeps everyone calmer and cuts down on conflict later. You don’t need to share every single detail of the process. Just enough to show things are actually moving.
Nobody expects an estate to wrap up overnight. But people do expect honesty along the way. A short email saying things are still in progress carries more weight than most executors realize.
Avoid Mixing Funds
This one sounds obvious, and yet it happens all the time anyway. Estate funds and personal funds should never blend together, not even briefly, not even for something small and seemingly harmless. Keep the estate in its own separate account. Track every transaction carefully, no matter how minor it seems. Blur these lines, even with the best of intentions, and you risk serious legal trouble along with personal liability that can trail you long after the estate closes for good.
Estate administration was never about perfection. It’s about staying careful, organized, and honest through a process that rarely feels either. Build a clear inventory. Respect the deadlines. Keep beneficiaries in the loop, avoid mixing funds, and lean on professional guidance when things get genuinely complicated. Do this well, and you’ll spare yourself a lot of stress, plus a few awkward family conversations nobody wants to sit through twice.

Whether it is credit evaluation, portfolio diversification, stress testing, or regulations, the course provides the candidate with relevant information that they can apply within their environment. Through understanding the approaches for credit risk management, FRM full form (Financial Risk Management) students gain the capacity to perform the analysis necessary for making credit decisions and minimising losses.
Key Credit Risk Management Strategies Each FRM Course Candidate Must Know
1. Understand Fundamentals of Credit Risk Assessment
Every student who enrolls for the FRM course should first learn how to analyse credit risks. Credit risks refer to the potential inability of a counterparty or borrower to pay back debts. The creditworthiness of borrowers is determined by taking into consideration aspects like the borrowing record, cash flows, financial statements, industrial performance and debt level.
Apart from the evaluation of numerical data, students need to learn other forms of assessments. Quality of management, market standing, corporate governance and the economic environment contribute towards the creditworthiness of borrowers.
2. Master Credit Rating Models and Scorecards
The credit score models are critical in evaluating the financial soundness of the borrowing party. The FRM full form (Financial Risk Management) course educates students on the internal credit scoring model and external rating system of financial organisations and agencies. The credit score models calculate the likelihood of default through variables such as stable income, leverage, behaviour pattern, and liquidity.
It is equally important to understand how the credit ratings affect loan issuance processes, regulations, and capital allocation. Students should also appreciate the limitations of rating models since unexpected market occurrences could also affect the borrower’s performance.
3. Diversify Credit Portfolios to Reduce Concentration Risk
An example of credit risk management is portfolio diversification! This occurs when there are loans or investments that are focused on one particular area, which exposes an organisation to economic risk.
The FRM course will enable students to know how to measure the risks in the portfolio, such as through the analysis of sectors and correlation. The financial institution will benefit from maintaining a diversified portfolio through stability in profits.
4. Use Credit Risk Mitigation Techniques
Financial institutions use different strategies that mitigate the risks associated with credit. Some of these strategies include collateral, guarantee, netting, credit derivatives, and credit insurance. In all these cases, the risk for the lender is reduced should the borrower fail to settle their financial obligations.
It is the task of the students to establish when it is appropriate to use such strategies. The FRM designation addresses the legal issues surrounding the use of these strategies.
5. Conduct Regular Stress Testing and Scenario Analysis
The concept of stress testing allows companies to study the performance of their credit portfolios in difficult economic environments such as recessions, high-interest rates, and other types of geopolitical risks.
Scenario analysis works together with stress testing by exploring many potential scenarios that may influence the ability of borrowers to repay debts. Both concepts discussed in this FRM course allow companies to be more prepared for potential risk situations.
6. Monitor Counterparty and Industry Risks Continuously
Credit risk management does not stop there once the loan is granted! Continuous monitoring is required because the financial position of the borrower can be influenced by changes in the market environment, challenges in running their business or problems in the specific industry they belong to.
It is also necessary for them to understand the assessment of risks related to the whole industry as well as macroeconomic conditions impacting the borrower.
7. Stay Updated with Regulatory Standards and Risk Frameworks
Compliance with regulations is one of the key aspects of modern credit risk management. There are international rules like Basel rules which lay down the requirements of capital adequacy, risk measurement, and reporting. The FRM full form (Financial Risk Management) enables candidates to have the understanding necessary to gauge how these requirements change and affect banks.
Apart from regulatory compliance, candidates need to learn about new developments in technology, artificial intelligence, data analytics, and ESG factors that influence credit risk management.
Final Takeaway
Credit risk management is an essential tool that every FRM professional needs, making it an integral part of the FRM learning process. By determining credit assessment techniques, regulatory frameworks, portfolio diversification and risk mitigation tools, FRM course students can build the expertise needed to make informed financial decisions and manage risk in dynamic markets.
Are you looking to build a successful career in finance risk management? Join Zell Education’s FRM program to learn from industry experts, gain practical insights and prepare for FRM exams while developing in-demand risk management skills.
FAQs
1. Which credit risk models should FRM students know?
FRM students must learn models such as Probability of Default (PD), Exposure at Default (EAD), and Loss Given Default (LGD).
2. How does portfolio diversification reduce credit risk?
Diversification of risks distributes the risk among different borrowers and industries.
3. Why is it important for FRM students to learn about credit risk management?
Credit risk management helps FRM students acquire skills in financial risk management.
____________________________________________________________________________
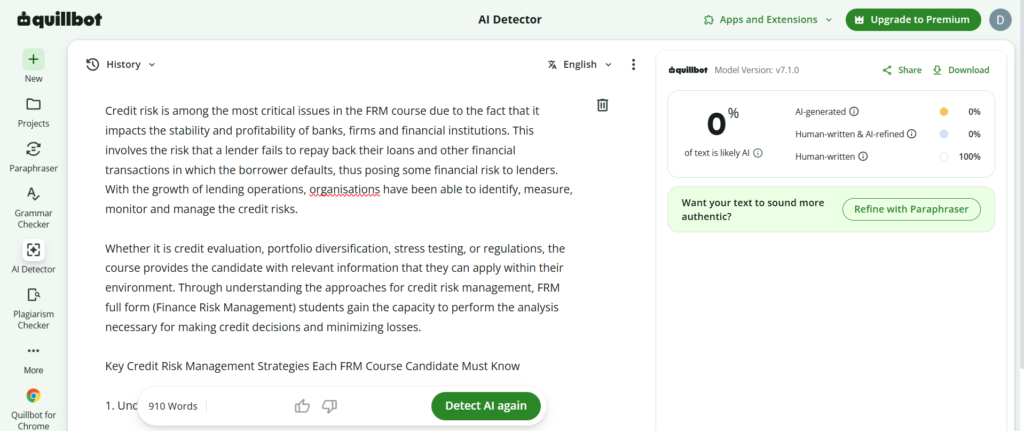
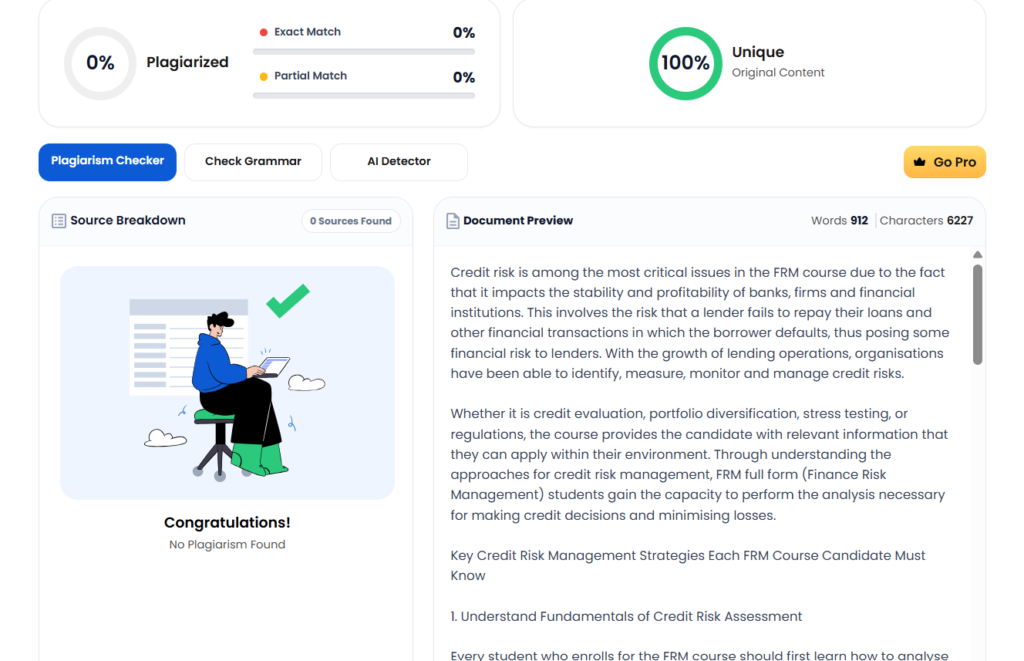
Quillbot Report
Plagiarism Report


-
 Celebrity1 year ago
Carolin Bacic: Life, Biography, Family, and Legacy
-
 Celebrity6 months ago
Alex Eala: Rising Tennis Star from the Philippines and Her Journey to Global Success
-
 Celebrity2 years ago
Christine Williamson: A Rising Star in Sports Journalism
-
 Celebrity12 months ago
Dani Daniels: A Complete Biography of the Artist, Media Personality, and Entrepreneur
-
 Celebrity6 months ago
Valerie Perrine: A Complete Biography of the Acclaimed Actress and Icon
-
 Celebrity10 months ago
Eleonora Incardona: Biography, Career, Age, Boyfriend, Net Worth & Lifestyle (2025)
-
 Celebrity2 years ago
Vera Davich: Biography, Life, and Legacy2025
-
 Celebrity10 months ago
Ari Kytsya: Biography, Career, Age, Lifestyle & Rise as a Global Social Media Star