Business
The Role of Land Promoters in Unlocking Development Potential

Land promoters are an important and expert part of the dynamic property development world of turning raw land into a valuable development opportunity. They mediate between the land owners and the developers, providing experience in planning, technical planning, and market positioning, which adds a lot of value to the land. This is a detailed guide on the role of land promoters, the strategic land promotion process, the advantages of land promotion, and what the landowners ought to take into consideration when using the services of a land promoter in the UK.
What Is a Land Promoter?
A land promoter is an expert professional or organisation that collaborates with the landowners in order to discover, evaluate, and develop the land using the planning process. Their main aim is to add value to their land by obtaining planning permission to build more valuable properties, e.g., residential or commercial property, but sell the land at an open market value to housebuilders or developers.
Whereas many landowners cannot or would not take this step, land promoters absorb the expense, risk, and complexity of the planning system.
The Importance of Strategic Land Promotion
The UK housing and development industry is relying heavily on strategic land promotion as part of its foundation. It allows the land owners who lack planning knowledge and capital to realise the potential of their land and, at the same time, make sure that housing requirements locally are met by providing much-needed sites which are ready to be converted into homes and are prepared to be built.
Promoters also help to raise the supply of housing as they prepare sites that are more enticing to the builders, hence the delay that comes with the speculative planning application is minimised.
How Land Promoters Maximise Land Value
A combination of planning, market understanding, and technical analysis is used by land promoters to make the most out of land. Here’s how:
Site Assessment and Appraisal
The land promoter will first carry out a careful analysis of the site before any work of promotion is initiated, including the location, access, environmental constraints, and planning policy environment.
Development of Strategy Planning
The planning strategy is developed, and it can consist of making applications for outline or full planning permission based on the potential of the site.
Technical and Supporting Work
All the technical reports, surveys, and community engagement that are necessary to support the planning application are organised by the promoters.
Authorities Negotiation
It is also important to make a proper involvement with the local authorities and statutory consultees to overcome hurdles and get a favourable decision in planning.
Marketing to Developers
After gaining consent, the land promoters sell the site to a group of housebuilders and developers, whereby they negotiate the best possible price.
The Land Promotion Process Explained
The general land promotion procedure includes a number of stages:
Initial Consultation
The promoter sits with the landowner to negotiate the goals and appraise the prospects of growth.
Promotion Agreement
It is executed in a legally binding agreement, which outlines duties, cost sharing, allocation of risks, and division of proceeds in the event of the sale of the land.
Planning Submission
The promoter makes and deposits a planning application, which may take several months or years.
Securing Planning Consent
After getting the planning permission, the promoter collaborates with agents to create a sales pack that shows the prospects of the site.
Sale to Developer
Lastly, the site is sold and promoted to a developer, and both the promoter and the owner of the land are given their portion of the sale price.
This top-to-bottom process is a skill that needs perseverance and subtle knowledge of the local planning landscape.
Strategic Advantages of Using Land Promoters
UK Planning System Expert Leadership
The UK planning system is infamously complicated. Land promoters simplify this situation by assuming responsibility for planning risk and enhancing the chances of getting permission from landowners.
None of the preliminary expenses are to the Landowners
The majority of land promotion deals are no-cost unless successful, and as such, the promoters bear the entire planning expenses and receive them back during the sale.
Approach to Developer Networks
Promoters have built contacts with as many developers as possible: national housebuilders, regional specialists, increasing the chances of sales.
Enhanced Land Value
Promoters will achieve a better sale price when they acquire planning permission and offer land that is more marketable than when they sell the land without permission.
Responsibilities of Land Promoters
Land promoters must:
- Carry out due diligence and preliminary site survey.
- Formulate a realistic planning strategy.
- Connect with governments and societies.
- Manage technical work and professional reports.
- Control the planning application process.
- Advertise the site to developers.
- Secure optimal sale terms.
They do not build the development, but prepare the ground upon which developers can then build the development effectively.
What Landowners Should Consider
Before enlisting the services of a land promoter, the landowners ought to take into consideration:
Promotion Agreement Terms
Get to know how the costs, risks, and profits are going to be shared.
Timescale
Planning and promotion may take a long time- years.
Market Conditions
The changes in the planning policy and market demand affect land value.
Professional Advice
Independent legal, tax, and planning advice should be sought to guarantee the optimum.
The Role of LPDF and Industry Standards
The Land, Planning and Development Federation (LPDF) is an organisation comprising leading land promotion companies in the UK and best practice lobbying of the industry, which advances high standards in planning, technical rigour, and ethical behaviour in the profession. Members will play an important role in improving the supply of development land.
Final Thoughts – Unlocking Land Potential with Expertise
In a constantly challenging planning environment, land promoters offer a strategic, knowledgeable route to help landowners maximise their assets. Through risk absorption, going through the planning system, and taking advantage of market-ready strategies, land promoters are enhancing the connection between land ownership and successful and responsible development.
A good land promoter can be a turning point for landowners who want to see the full potential of their location, without any doubt.


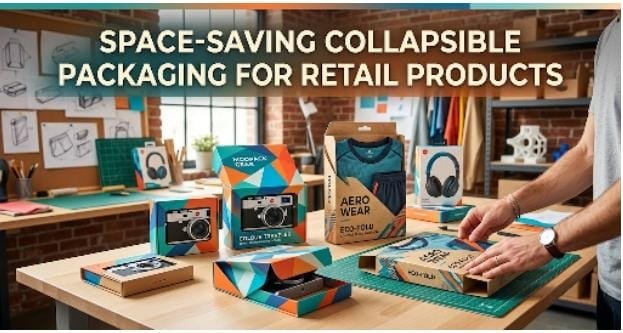
The storage of products is expensive. Not only is warehouse space costly, but there is also a cost to storing goods. Products that are kept in a box just waiting to be filled are a problem. After they are done waiting, the final bill will remind you of it.
Here’s how collapsible rigid packaging makes its case. It folds away to a small package when not in use, and snaps back when it needs to be. Not complicated, and an excellent problem-solver.
What Collapsible Packaging Actually Solves
Standard rigid boxes have a footprint based on their contents or lack thereof. A hundred flat-packed boxes makes for a nicely stacked pile on a warehouse pallet. The same hundred pre-formed boxes makes for an expensive and large shipment of mostly air.
Collapsible packaging avoids that entirely. Flat when stored, shipped, or moved between facilities. Formed only when a product actually needs to go inside it.
Retailers running multiple locations feel this the most. Stockrooms are small. Shelf space is smaller still. Packaging that folds down to a fraction of its assembled size means more room for stock, not boxes.
Retail Products That Benefit Most
Not every product needs this. Heavy, bulky items usually ship fine in standard cartons.
Where collapsible packaging really shines is smaller retail goods. Cosmetics, accessories, homeware, gift items. Anything sold in reasonably high volume, where storage space adds up fast across hundreds or thousands of units.
Seasonal retail stock benefits too. A shop ordering extra packaging ahead of a busy period does not want a stockroom full of assembled boxes sitting there for weeks. Flat-packed packaging for products waiting for a seasonal rush takes up a fraction of the space.
Design Considerations That Actually Matter
Collapsible does not mean flimsy. A well-designed fold structure still protects the product properly once assembled.
Reinforced fold lines matter here and locking tabs help too. A box that folds into shape and locks without tape saves time on the shop floor. Staff assembling stock during a busy period do not want to be hunting for a tape gun every few minutes.
Branding Does Not Have to Suffer
There is a myth that collapsible designs limit branding options. Not really true anymore.
Print quality on flat-packed packaging for products matches standard cartons. The branding gets applied before the fold lines are cut, so logos, colours, and finishes look exactly as intended once the box is assembled. Customers browsing a shelf would not necessarily know the box folded flat before it reached the store.
Shipping and Storage Savings, Properly Broken Down
Flat-packed boxes are able to be packed more tightly on a pallet which reduces the number of lorries required for transportation reducing costs directly
Storage costs drop too. A stockroom holding flat packaging instead of assembled boxes can fit considerably more stock in the same footprint. For retailers paying for warehouse space by the square metre, this is not a small saving. It adds up across a full year of orders.
Handling time changes as well. Staff assembling packaging on demand only fold up the boxes that you need for that day’s stock, rather than storing pre set boxes that may sit idle without use for days.
Where It Falls Short
Worth being honest about this. Assembly takes staff time. Someone has to fold and lock each box before it comes in use, which is an extra step that pre-formed cartons do not require.
For very high-volume operations shipping thousands of units daily, that assembly time needs factoring into labour costs. It is not always the right fit for every business, particularly ones without spare hands during peak periods.
Getting It Right
Custom rigid boxes is most useful when dealing with small items, irregular sales throughout the year, and/or limited storage space. It’s also important to consider the additional labour that you need to assemble the package, though it’s probably worth testing on a small scale.
Ask the manufacturer to provide samples before investing in a large set. It’s a good idea to check the strength of a folded box, print quality, and how easy it is to open during a test run.
Good packaging for products does not have to sit around taking up space it is not using. Flat when it is not in need. Solid when it is. That is really the whole appeal.

Estate administration sounds simple on paper. Someone passes away, their wishes get carried out, everyone moves on with their lives. Reality rarely cooperates that neatly. Paperwork piles up. Emotions run high, sometimes higher than anyone expected. And small mistakes have a way of snowballing into legal headaches nobody saw coming. Handling an estate well takes patience. It also takes a fair amount of stubbornness, if we’re being honest.
Start by understanding what you’re actually on the hook for. Executors often assume the job is just handing out belongings and closing a few accounts. It isn’t. Debts need settling. Taxes need filing. Beneficiaries need notifying, all on a timeline that couldn’t care less about your schedule or your energy level that week. Many executors find real value in discussing your case with a probate attorney early, before the mistakes happen instead of after. That’s not weakness. It’s just common sense, sort of like reading the manual before assembling furniture, instead of winging it and ending up with three mystery screws and a wobbly shelf.
Don’t Skip the Inventory
Rushing through the asset inventory ranks among the biggest mistakes people make. Skipping it almost entirely ranks right up there too. Every account, every property, every possession needs clear documentation before anything gets distributed to anyone. Skip this step, even by accident, and you’ve opened the door to disputes down the road. Family members remember things differently. Especially when money enters the picture. A thorough inventory protects everyone involved, including you as the executor, from accusations that something went missing or got mishandled somewhere along the way.
So take photos of everything. Write it all down, even the details that seem painfully obvious in the moment. Arguments six months from now have a strange habit of hinging on exactly the kind of detail nobody bothered to record.
Watch Out for Deadlines
Estate administration comes loaded with deadlines, more than most people expect going in. Tax filings. Creditor notifications. Court paperwork with its own quiet clock ticking in the background. Miss one, and real problems follow, sometimes financial, sometimes legal, sometimes both at once. Set reminders wherever you can. Don’t lean on memory alone, because grief has an odd way of making even the simplest dates slip through the cracks.
Feeling overwhelmed by all of it? Break the deadlines into smaller pieces instead of staring at the whole pile. Tackle the tax paperwork one week, then the creditor notices the next. Slow and steady wins here, almost every single time.
Communicate With Beneficiaries
Silence breeds suspicion, plain and simple. Go months without an update, and beneficiaries start assuming the worst. Honestly, who could blame them? Regular communication, even something brief, keeps everyone calmer and cuts down on conflict later. You don’t need to share every single detail of the process. Just enough to show things are actually moving.
Nobody expects an estate to wrap up overnight. But people do expect honesty along the way. A short email saying things are still in progress carries more weight than most executors realize.
Avoid Mixing Funds
This one sounds obvious, and yet it happens all the time anyway. Estate funds and personal funds should never blend together, not even briefly, not even for something small and seemingly harmless. Keep the estate in its own separate account. Track every transaction carefully, no matter how minor it seems. Blur these lines, even with the best of intentions, and you risk serious legal trouble along with personal liability that can trail you long after the estate closes for good.
Estate administration was never about perfection. It’s about staying careful, organized, and honest through a process that rarely feels either. Build a clear inventory. Respect the deadlines. Keep beneficiaries in the loop, avoid mixing funds, and lean on professional guidance when things get genuinely complicated. Do this well, and you’ll spare yourself a lot of stress, plus a few awkward family conversations nobody wants to sit through twice.

Whether it is credit evaluation, portfolio diversification, stress testing, or regulations, the course provides the candidate with relevant information that they can apply within their environment. Through understanding the approaches for credit risk management, FRM full form (Financial Risk Management) students gain the capacity to perform the analysis necessary for making credit decisions and minimising losses.
Key Credit Risk Management Strategies Each FRM Course Candidate Must Know
1. Understand Fundamentals of Credit Risk Assessment
Every student who enrolls for the FRM course should first learn how to analyse credit risks. Credit risks refer to the potential inability of a counterparty or borrower to pay back debts. The creditworthiness of borrowers is determined by taking into consideration aspects like the borrowing record, cash flows, financial statements, industrial performance and debt level.
Apart from the evaluation of numerical data, students need to learn other forms of assessments. Quality of management, market standing, corporate governance and the economic environment contribute towards the creditworthiness of borrowers.
2. Master Credit Rating Models and Scorecards
The credit score models are critical in evaluating the financial soundness of the borrowing party. The FRM full form (Financial Risk Management) course educates students on the internal credit scoring model and external rating system of financial organisations and agencies. The credit score models calculate the likelihood of default through variables such as stable income, leverage, behaviour pattern, and liquidity.
It is equally important to understand how the credit ratings affect loan issuance processes, regulations, and capital allocation. Students should also appreciate the limitations of rating models since unexpected market occurrences could also affect the borrower’s performance.
3. Diversify Credit Portfolios to Reduce Concentration Risk
An example of credit risk management is portfolio diversification! This occurs when there are loans or investments that are focused on one particular area, which exposes an organisation to economic risk.
The FRM course will enable students to know how to measure the risks in the portfolio, such as through the analysis of sectors and correlation. The financial institution will benefit from maintaining a diversified portfolio through stability in profits.
4. Use Credit Risk Mitigation Techniques
Financial institutions use different strategies that mitigate the risks associated with credit. Some of these strategies include collateral, guarantee, netting, credit derivatives, and credit insurance. In all these cases, the risk for the lender is reduced should the borrower fail to settle their financial obligations.
It is the task of the students to establish when it is appropriate to use such strategies. The FRM designation addresses the legal issues surrounding the use of these strategies.
5. Conduct Regular Stress Testing and Scenario Analysis
The concept of stress testing allows companies to study the performance of their credit portfolios in difficult economic environments such as recessions, high-interest rates, and other types of geopolitical risks.
Scenario analysis works together with stress testing by exploring many potential scenarios that may influence the ability of borrowers to repay debts. Both concepts discussed in this FRM course allow companies to be more prepared for potential risk situations.
6. Monitor Counterparty and Industry Risks Continuously
Credit risk management does not stop there once the loan is granted! Continuous monitoring is required because the financial position of the borrower can be influenced by changes in the market environment, challenges in running their business or problems in the specific industry they belong to.
It is also necessary for them to understand the assessment of risks related to the whole industry as well as macroeconomic conditions impacting the borrower.
7. Stay Updated with Regulatory Standards and Risk Frameworks
Compliance with regulations is one of the key aspects of modern credit risk management. There are international rules like Basel rules which lay down the requirements of capital adequacy, risk measurement, and reporting. The FRM full form (Financial Risk Management) enables candidates to have the understanding necessary to gauge how these requirements change and affect banks.
Apart from regulatory compliance, candidates need to learn about new developments in technology, artificial intelligence, data analytics, and ESG factors that influence credit risk management.
Final Takeaway
Credit risk management is an essential tool that every FRM professional needs, making it an integral part of the FRM learning process. By determining credit assessment techniques, regulatory frameworks, portfolio diversification and risk mitigation tools, FRM course students can build the expertise needed to make informed financial decisions and manage risk in dynamic markets.
Are you looking to build a successful career in finance risk management? Join Zell Education’s FRM program to learn from industry experts, gain practical insights and prepare for FRM exams while developing in-demand risk management skills.
FAQs
1. Which credit risk models should FRM students know?
FRM students must learn models such as Probability of Default (PD), Exposure at Default (EAD), and Loss Given Default (LGD).
2. How does portfolio diversification reduce credit risk?
Diversification of risks distributes the risk among different borrowers and industries.
3. Why is it important for FRM students to learn about credit risk management?
Credit risk management helps FRM students acquire skills in financial risk management.
____________________________________________________________________________
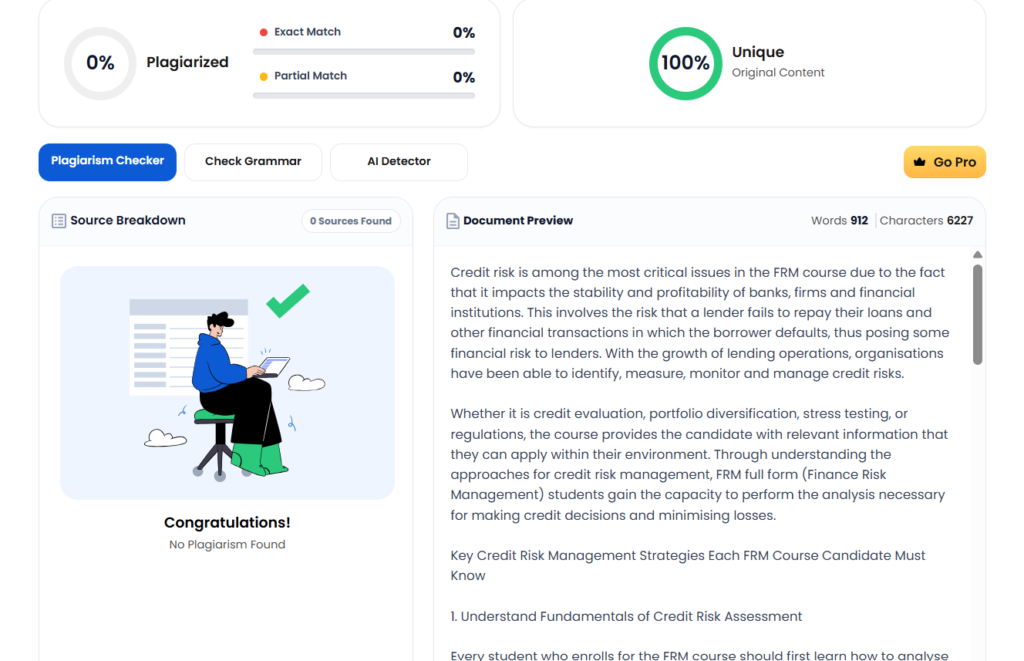
Quillbot Report
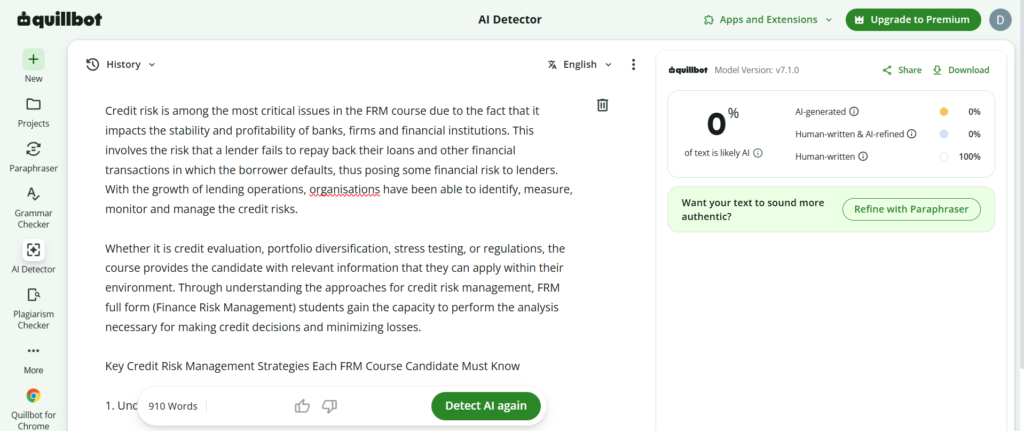
Plagiarism Report


-
 Celebrity1 year ago
Carolin Bacic: Life, Biography, Family, and Legacy
-
 Celebrity6 months ago
Alex Eala: Rising Tennis Star from the Philippines and Her Journey to Global Success
-
 Celebrity2 years ago
Christine Williamson: A Rising Star in Sports Journalism
-
 Celebrity12 months ago
Dani Daniels: A Complete Biography of the Artist, Media Personality, and Entrepreneur
-
 Celebrity6 months ago
Valerie Perrine: A Complete Biography of the Acclaimed Actress and Icon
-
 Celebrity10 months ago
Eleonora Incardona: Biography, Career, Age, Boyfriend, Net Worth & Lifestyle (2025)
-
 Celebrity2 years ago
Vera Davich: Biography, Life, and Legacy2025
-
 Celebrity10 months ago
Ari Kytsya: Biography, Career, Age, Lifestyle & Rise as a Global Social Media Star